THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

Decree No. 90/2025/NĐ-CP dated April 14, 2025 of the Government amending and supplementing certain provisions guiding the implementation of the Law on Independent Audit.

1. Add enterprises and organizations whose annual financial statements are required by law to be audited.

Other large-scale enterprises which meet at least two out of the following three criteria:

- Having an average annual number of employees participating in social insurance of over 200;

- Having annual total revenue exceeding VND 300 billion;

- Having total assets exceeding VND 100 billion.

The enterprises subject to the above-mentioned regulations that fail to meet the criteria for being classified as large-scale enterprises for two consecutive years shall not be required to undergo mandatory audits until they once again meet the prescribed criteria.

Principles for determining the average number of employees participating in social insurance per year, annual total revenue, and total assets:

a) The number of employees participating in social insurance includes all employees managed, employed, and paid wages or salaries by the entity, who are covered under social insurance in accordance with the laws on social insurance;

b) The average number of employees participating in social insurance per year is calculated by taking the total number of employees participating in social insurance for all months of the preceding year and dividing by 12 months;

c) The number of employees participating in social insurance for a given month is determined at the end of that month and is based on the social insurance contribution documents submitted by the enterprise to the social insurance agency;

d) The annual total revenue is determined based on the annual financial statements of the preceding year, which are prepared by the entity in accordance with accounting laws;

đ) The total assets are determined at the end of the financial year based on the annual financial statements of the preceding year, which are prepared by the entity in accordance with accounting laws.

2. Amendment regarding the audit report signing period by auditors:

A practicing auditor is not allowed to sign the audit report for a single audited entity for more than five consecutive years.


Share

Related news

CONTINUE TO REDUCE 2% VAT UNTIL THE END OF DECEMBER 2024

CONTINUE TO REDUCE 2% VAT UNTIL THE END OF DECEMBER 2024

INCREASE IN REGIONAL MINIMUM WAGES FROM 2026

INCREASE IN REGIONAL MINIMUM WAGES FROM 2026

THE 10% PERSONAL INCOME TAX

THE 10% PERSONAL INCOME TAX

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME

PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME EFFECTIVE FROM JANUARY 16, 2026

TIME LIMIT FOR SUPPLEMENTARY TAX DECLARATIONS: REDUCED FROM 10 YEARS TO 5 YEARS

TIME LIMIT FOR SUPPLEMENTARY TAX DECLARATIONS: REDUCED FROM 10 YEARS TO 5 YEARS

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

PROCEDURE FOR HANDLING ERRORS INVOICES ACCORDING TO DECREE 70/2025/ND-CP

PROCEDURE FOR HANDLING ERRORS INVOICES ACCORDING TO DECREE 70/2025/ND-CP

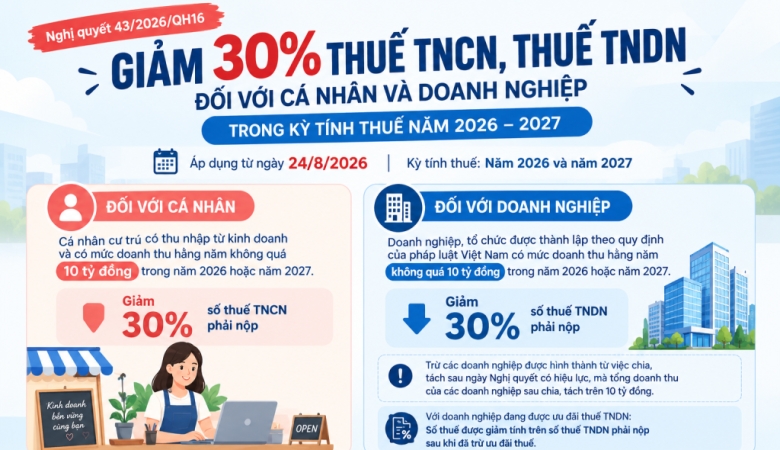
30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT FOR THE 2026-2027

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

EXTEND TIME LIMITS FOR PAYMENT OF TAX IN 2025

EXTEND TIME LIMITS FOR PAYMENT OF TAX IN 2025