Vietnamese
 English
 Korean
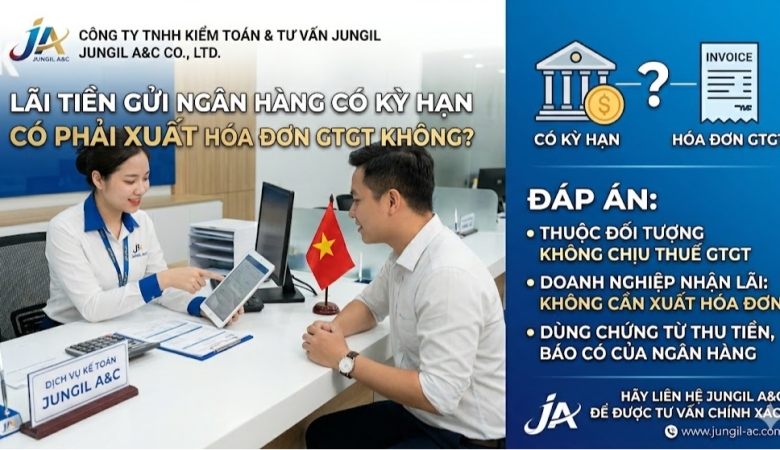
DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?
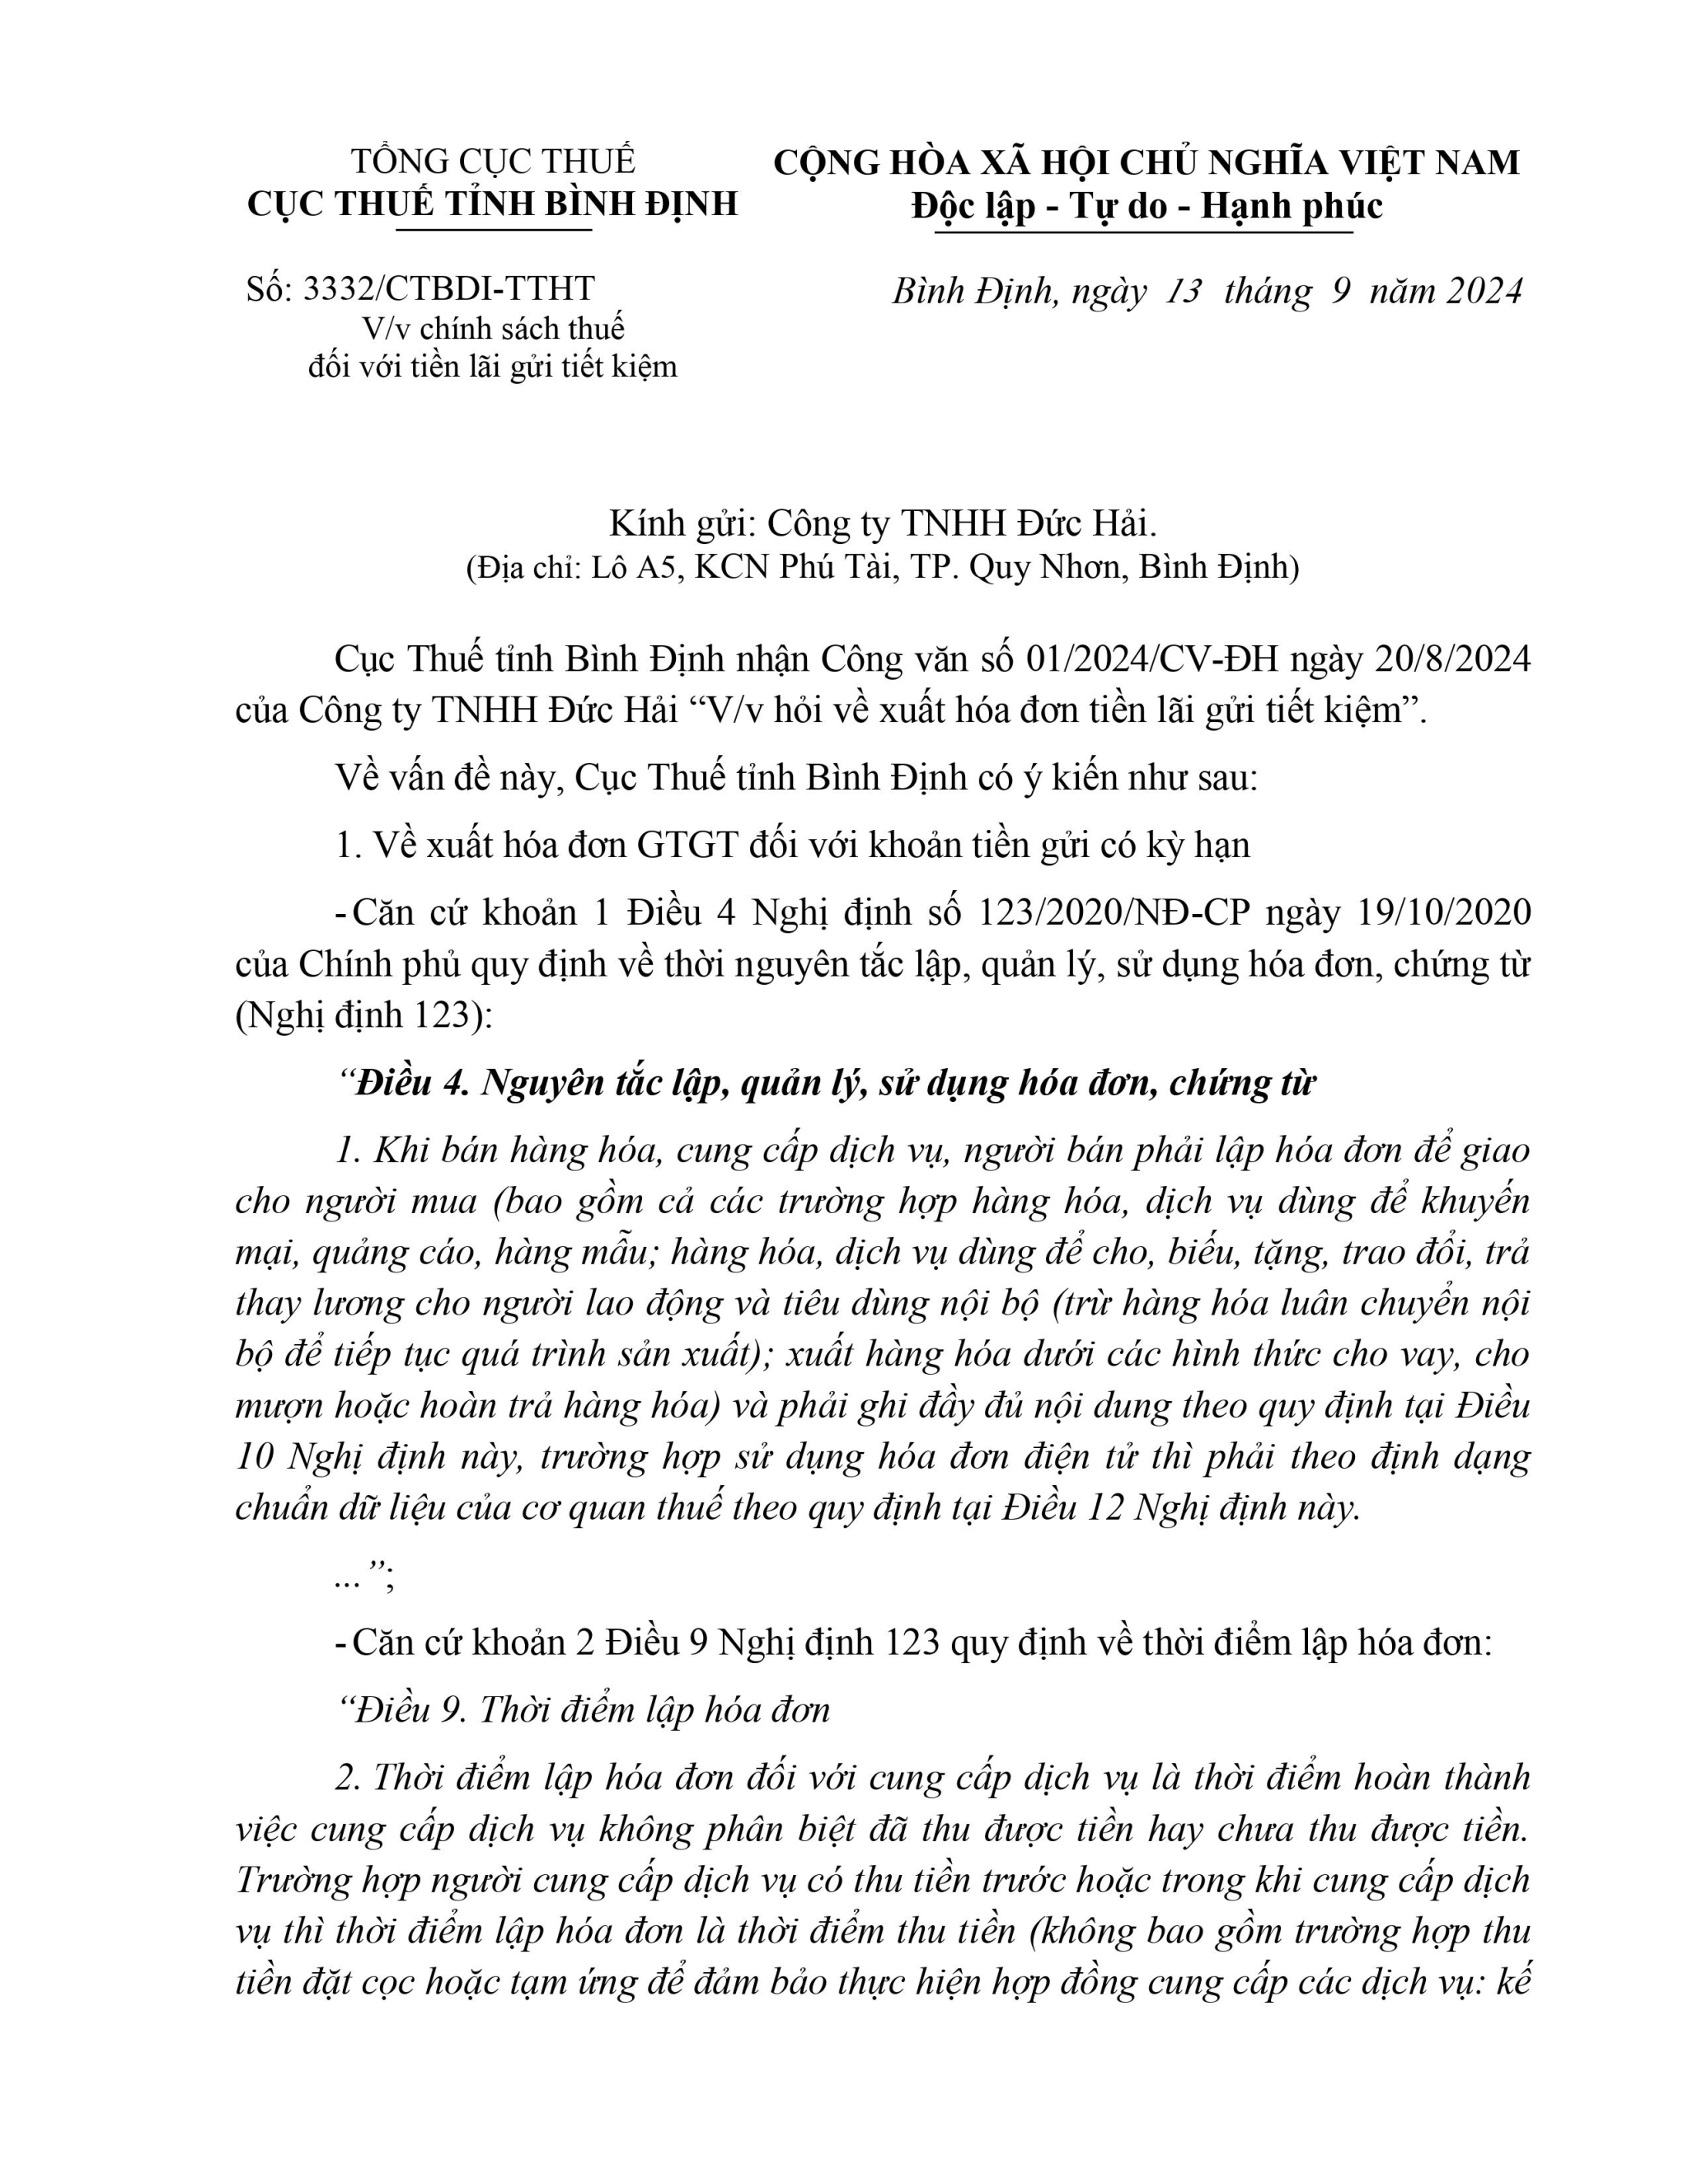
On September 13, 2024, Binh Dinh Provincial Tax Department issued Official Dispatch No. 3332/CTBDI-TTHT in response to the Enterprise regarding the issuance of invoices and declaration of VAT for term bank deposits as follows:
1. Issuing a VAT invoice on term deposits
- Pursuant to Clause 1, Article 4 of Decree No. 123/2020/ND-CP dated October 19, 2020 (Decree 123) of the Government stipulating the principles for issuing, managing and using invoices and documents.
- Pursuant to Clause 2, Article 9 of Decree 123 regulating the time of invoice issuance.
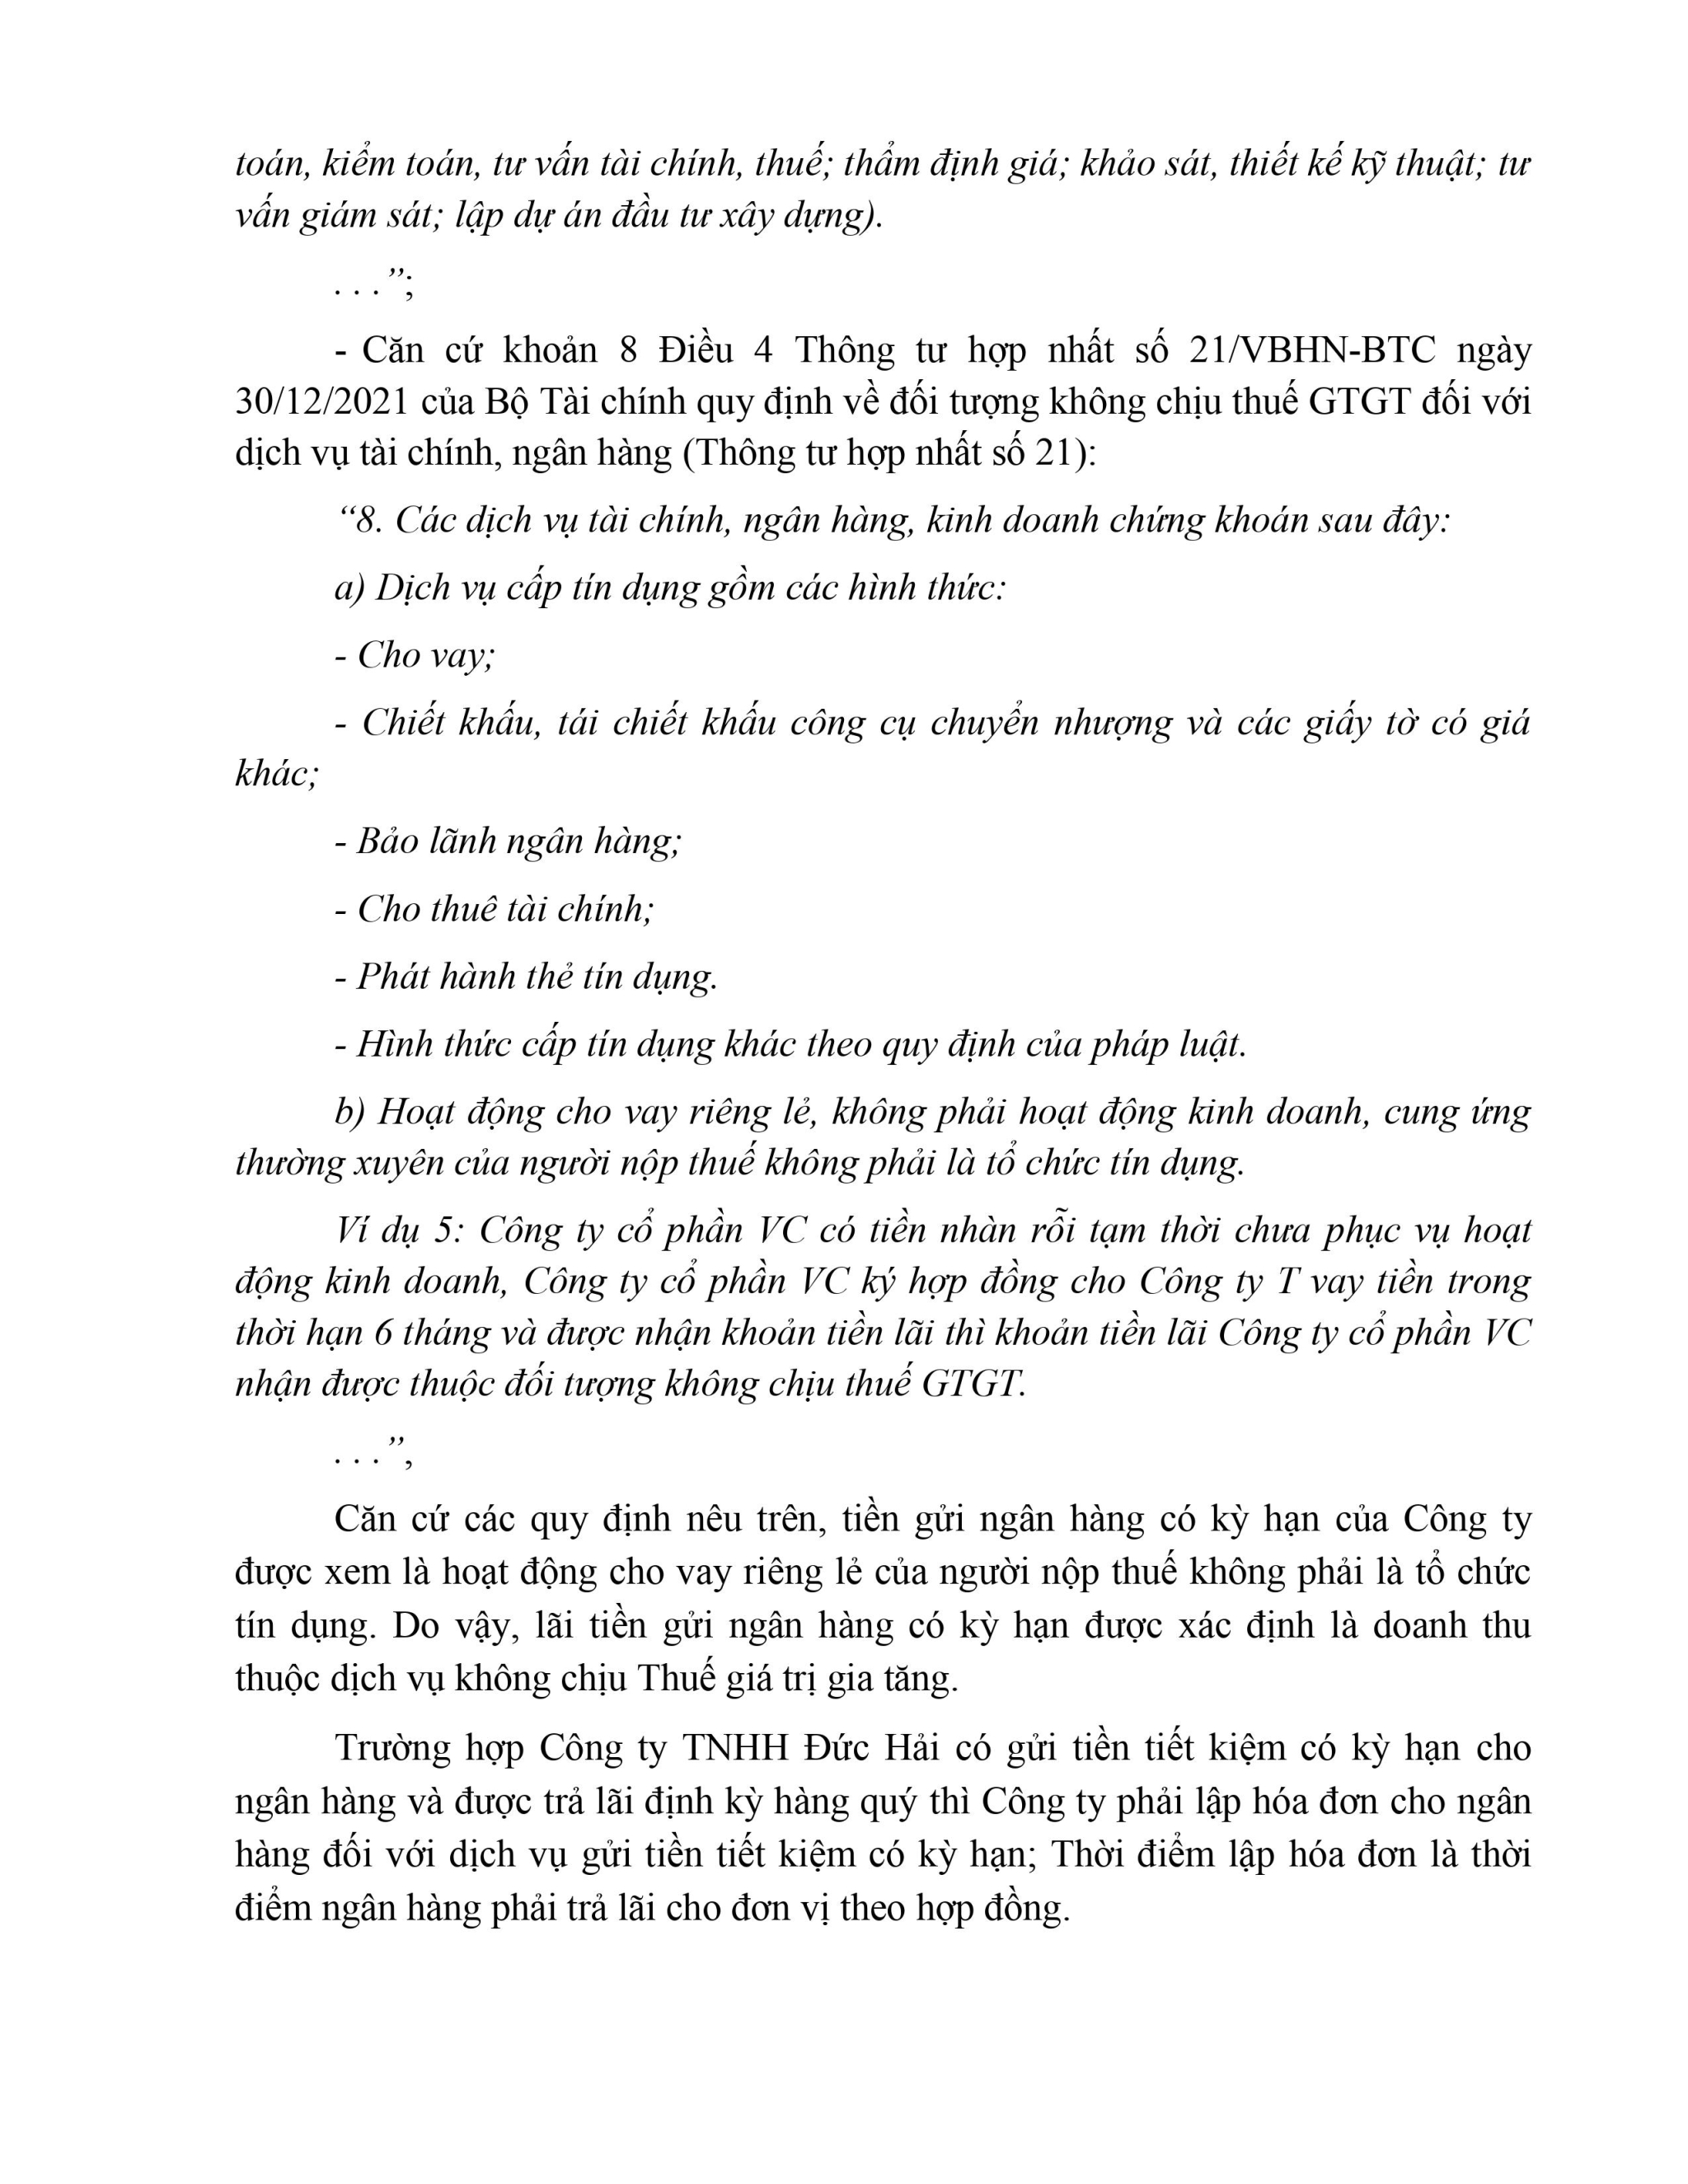
- Pursuant to Point b, Clause 8, Article 4 of Circular 219/2013/TT-BTC dated December 18, 2023 (Circular 219), Objects not liable to VAT for financial and banking services.
Based on the above provisions, the Company's term deposits are considered as individual lending activities of taxpayers that are not credit institutions. Therefore, the interest on term deposits is determined as service revenue not subject to Value Added Tax.
In case the Company makes a term deposit with the bank and receives quarterly interest payments, the Company must issue an invoice to the bank for the term deposit service; the time of invoice issuance is when the bank must pay interest to the Company according to the contract.
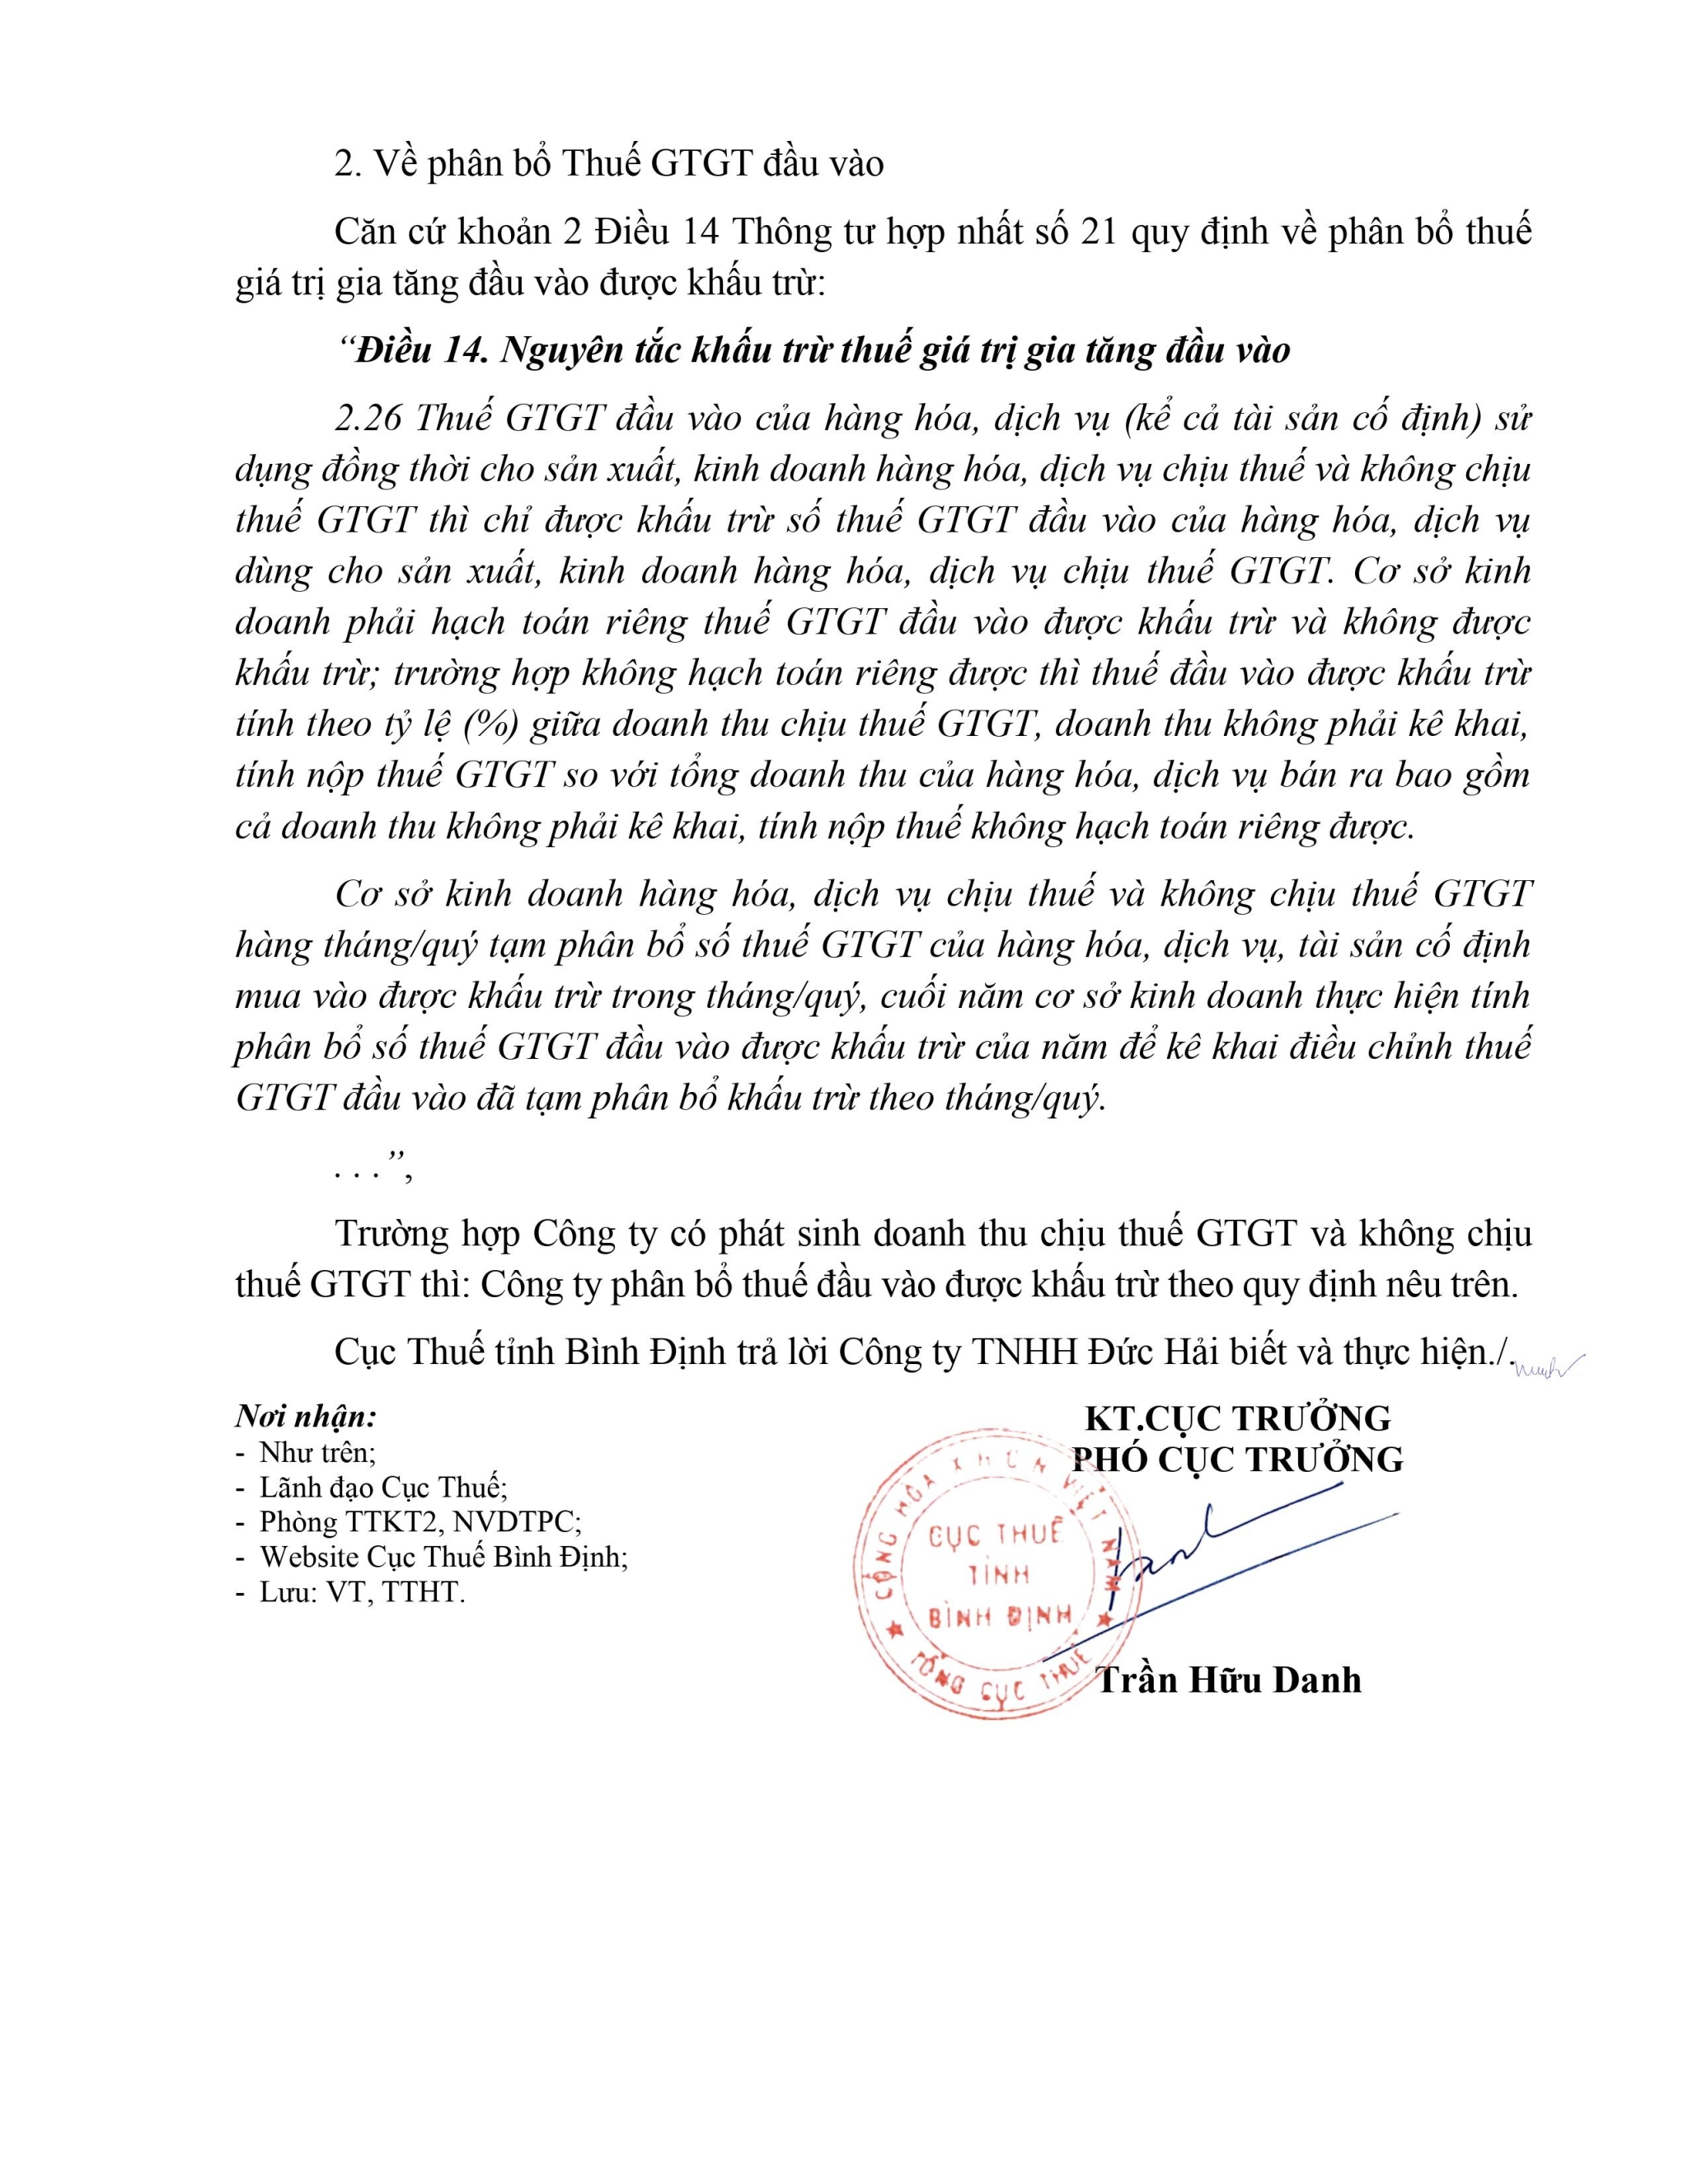
2. Allocation of input VAT
Pursuant to Clause 2, Article 14 of Circular 219 regulating the allocation of deductible input value added tax:
In case the Company has revenue for goods or services use for the production of and trading in both goods or services liable and not liable to VAT, the Company will separately account creditable and non-creditable VAT amounts; If it is impossible to do so, input VAT shall be credited based on the percentage (%) of VAT-liable turnover to total turnover of sold goods or services that cannot be separately accounted.