From 01 July 2026: Increase of Statutory Base Salary to VND 2,530,000 per Month

From 01 July 2026: Increase of Statutory Base Salary to VND 2,530,000 per Month

From 01 July 2026: Increase of Statutory Base Salary to VND 2,530,000 per Month

From 01 July 2026: Increase of Statutory Base Salary to VND 2,530,000 per Month and Adjustment of Maximum SI Contribution Base

On 15 May 2026, the Government issued Decree No. 161/2026/ND-CP regulating the statutory base salary and bonus regime applicable to officials, civil servants, public employees, and armed forces personnel.

1. Increase in Statutory Base Salary from 01 July 2026

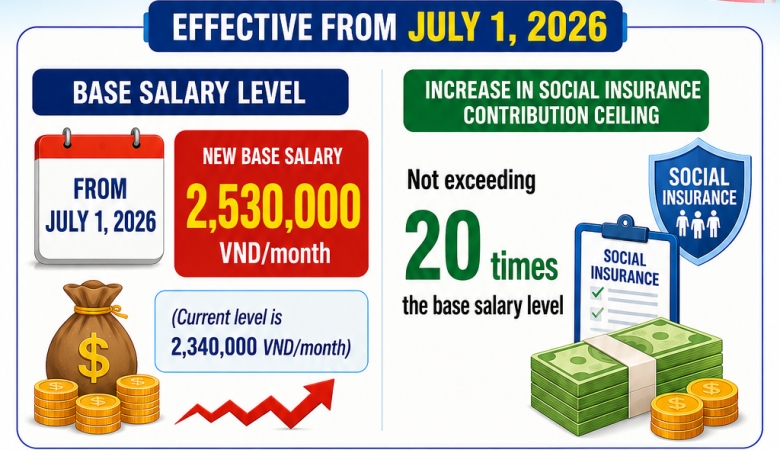
Under Decree 161/2026/ND-CP, effective from 01 July 2026, the statutory base salary will increase from VND 2,340,000/month to VND 2,530,000/month.

The statutory base salary serves as an important basis for:

  • Calculating salaries in the public sector;
  • Determining contribution and entitlement levels for certain insurance schemes;
  • Calculating various allowances and other financial obligations under Vietnamese laws.

2. Adjustment of Maximum Social Insurance Contribution Base

Under current regulations, the monthly salary used as the basis for compulsory social insurance contributions must not exceed 20 times the statutory base salary.

Accordingly, from 01 July 2026:

  • The maximum salary used as the basis for compulsory social insurance contributions will be: VND 50.600.000 per month

3. Key Considerations for Employers

Employers should review:

  • Employees’ salary levels for social insurance purposes;
  • Payroll and social insurance declaration systems;
  • Labor costs and HR budgets from July 2026 onward.
Timely updates will help enterprises ensure compliance with Vietnamese labor and social insurance regulations.

Share

Related news

THE SPOT IMPORT AND EXPORT GOODS CONDUCTED BEFORE 1 JULY 2025

THE SPOT IMPORT AND EXPORT GOODS

FOREIGN CONTRACTOR TAX

FOREIGN CONTRACTOR TAX ON SERVICES VIA E-COMMERCE CHANNELS AND DIGITAL PLATFORMS

VAT REFUND
VAT REFUND

RISK INFORMATION OF VAT REFUND

DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

EMPLOYEES' WELFARE
EMPLOYEES' WELFARE

EMPLOYEES' WELFARE

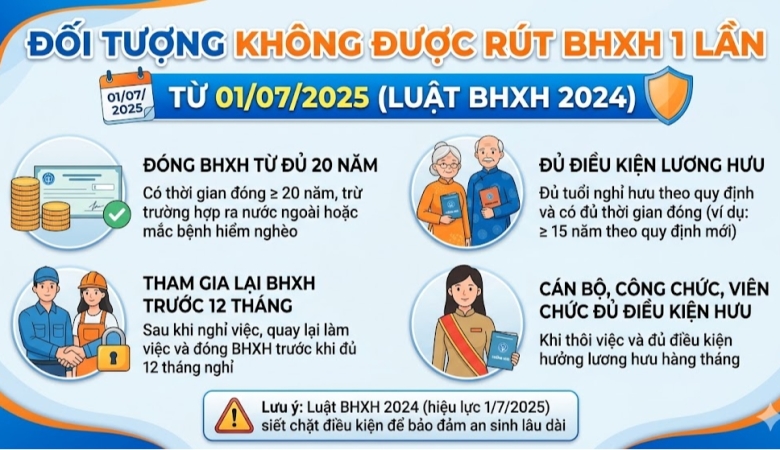
SUBJECTS WILL NOT BE ELIGIBLE FOR LUMP-SUM SOCIAL INSURANCE ALLOWANCE

SUBJECTS WILL NOT BE ELIGIBLE FOR LUMP-SUM SOCIAL INSURANCE ALLOWANCE

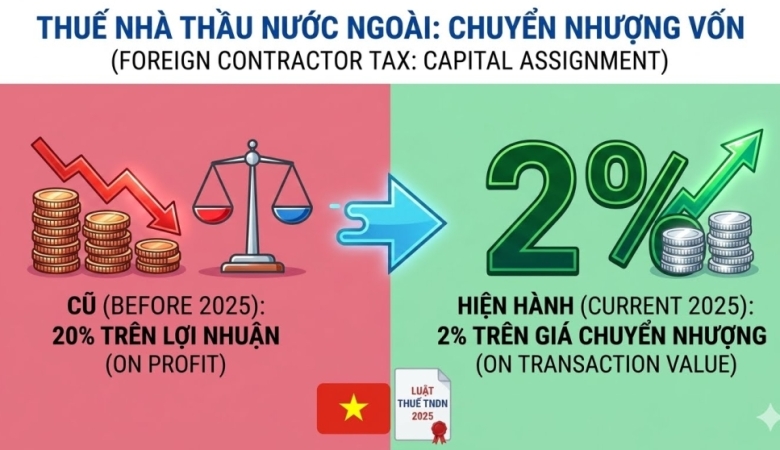
CAPITAL TRANSFER TAXATION

CAPITAL TRANSFER TAXATION

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

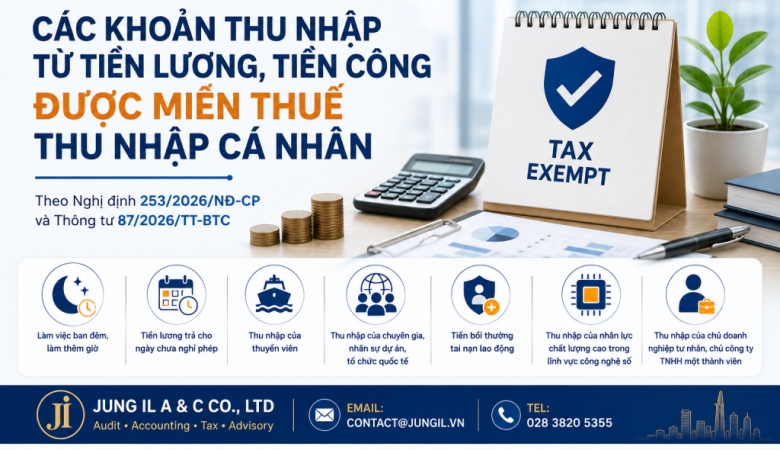
TAX-EXEMPT EMPLOYMENT INCOME

PERSONAL INCOME TAX

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

ACCOUNTING FOR MICRO ENTERPRISES

ACCOUNTING FOR MICRO ENTERPRISES