BIOMETRIC AUTHENTICATION REGULATIONS ON eTAX MOBILE

BIOMETRIC AUTHENTICATION REGULATIONS ON eTAX MOBILE

BIOMETRIC AUTHENTICATION REGULATIONS ON eTAX MOBILE

BIOMETRIC AUTHENTICATION REGULATIONS ON eTAX MOBILE

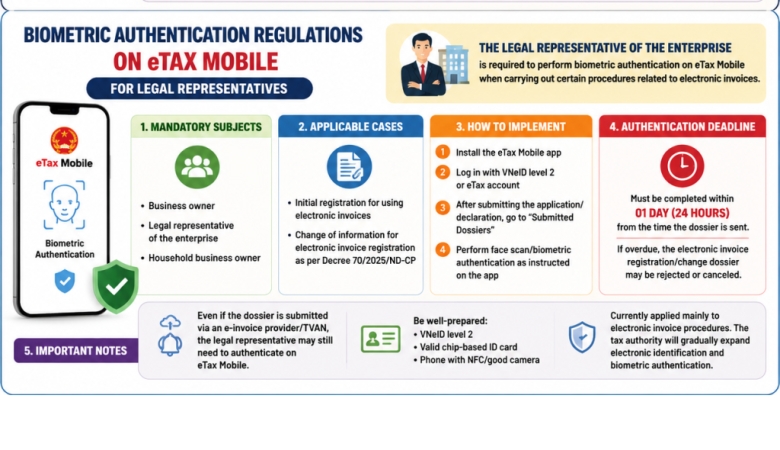
Currently, the tax authority is implementing biometric authentication requirements on the eTax Mobile application for certain electronic invoice procedures, particularly those involving the legal representative of an enterprise.

The main points are as follows:

Subjects required to complete biometric authentication:

  • Business owners
  • Legal representatives of enterprises
  • Household business owners

Applicable cases:

  • Initial registration for the use of electronic invoices
  • Changes to electronic invoice registration information in accordance with Decree No. 70/2025/ND-CP

Implementation procedure:

  • Install the eTax Mobile application
  • Log in using a Level 2 VNeID account or an electronic tax account
  • After submitting the application/declaration, access the “Submitted Dossiers” section
  • Perform facial scanning/biometric authentication following the instructions on the application

Authentication deadline:

  • In general, authentication must be completed within 01 day or 24 hours from the time the dossier is submitted
  • If the deadline is exceeded, the electronic invoice registration/change application may be rejected or cancelled

Practical notes:

  • Even if the enterprise submits the dossier through an e-invoice service provider or TVAN service provider, the legal representative may still be required to access eTax Mobile to complete biometric authentication
  • The legal representative should:
    • Have a Level 2 VNeID account
    • Possess a valid chip-based Citizen ID Card
    • Use a mobile phone with NFC/camera functionality to facilitate authentication

At present, this requirement mainly applies to electronic invoice procedures and not to all tax transactions on eTax. However, the tax authority is expected to gradually expand electronic identification and biometric authentication requirements for corporate taxpayers in the future.


Related news

CONTINUE TO REDUCE 2% VAT UNTIL THE END OF DECEMBER 2024

CONTINUE TO REDUCE 2% VAT UNTIL THE END OF DECEMBER 2024

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

TAX EXAMINATION, INSPECTION AT OFFICES OF TAXPAYERS

Tax examination, inspection at offices of taxpayers

PRINCIPLES OF CREATION OF INVOICES AND INVOICING TIME

Principles of creation of invoices and invoicing time

GLOBAL MINIMUN TAX IN VIETNAM

GLOBAL MINIMUN TAX IN VIETNAM

TIME FOR ISSUING INVOICES AND DECLARING REVENUE OF EXPORT GOODS

The time of issuing e-invoices and declaring revenue of export goods according to official letter No. 4890/TCT-KK

ISSUING ELECTRONIC INVOICES FOR RETURNED GOODS

Issuing electronic invoices for returned goods according to decree 123/2020/ND-CP

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

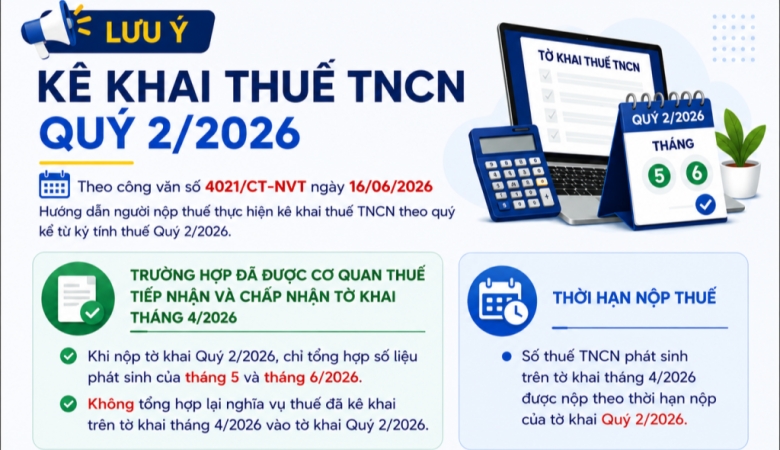
Q2/2026 PIT DECLARATION

Q2/2026 PIT DECLARATION

EMPLOYEES' WELFARE
EMPLOYEES' WELFARE

EMPLOYEES' WELFARE

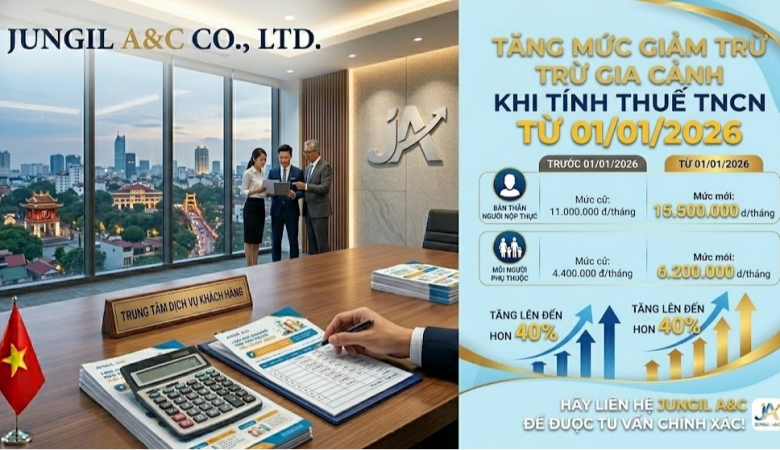
INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026

INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026