SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

Is the taxpayer allowed to declare supplementing the mount of refundable on the VAT declaration which submitted to the tax authority? And how to Declare in accordance with regulations?

Pursuant to the provisions of Point b, Clause 4, Article 7 of Decree No. 126/2020/ND-CP dated October 19, 2020 of the Government:

- If the supplementation leads to decrease in the amount of refundable VAT: the taxpayer may may submit the supplementary VAT declaration before submitting the VAT refund application. In case the VAT refund application has been submitted to the tax authority, the taxpayer must complete the procedure for canceling the VAT refund application before submitting the supplementing VAT declaration.

- If the supplementation leads to an increase in the amount of refundable VAT: the taxpayer may only increase the refundable VAT if the tax declaration dossier of the next period and the application for tax refund is not submitted.

Example: The VAT declaration period for the first quarter of 2024, A Company has a deductible VAT amount of 3 billion VND. On April 25, 2024, A Company prepared and submitted the VAT declaration for the first quarter of 2024 to the tax authority and received a notification of declaration acceptance from the system.

On July 31, 2024, the Company prepared and submitted the VAT declaration for the second quarter of 2024 after transferring the remaining deductible VAT for the first quarter of 2024 to the tax authority (having received a notification of declaration acceptance from the system).

- A Company prepare and declare the supplementing VAT declaration to increase in the amount of refundable VAT (including cases of adjustment due to not declaring the "proposed VAT refund amount" or having declared but adjusting it up due to errors) of the first quarter of 2024 before submitting the VAT declaration for the second quarter of 2024 (before July 31, 2024).

- A Company prepare and declare the supplementing VAT declaration to increase in the amount of refundable VAT after submitting the VAT declaration for the second quarter of 2024.

- A Company prepare and declare the supplementing VAT declaration to reduce the amount of refundable VAT before submitting the VAT refund application.


Related news

PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME

PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME EFFECTIVE FROM JANUARY 16, 2026

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS FROM JULY 1, 2026

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS

CANCELLATION OF VAT REFUND APPLICATIONS

CANCELLATION OF VAT REFUND APPLICATIONS AND CARRY-FORWARD OF VAT CREDITS

DEPENDENT REGISTRATION DOCUMENTS

DEPENDENT REGISTRATION DOCUMENTS

TAX EXAMINATION, INSPECTION AT OFFICES OF TAXPAYERS

Tax examination, inspection at offices of taxpayers

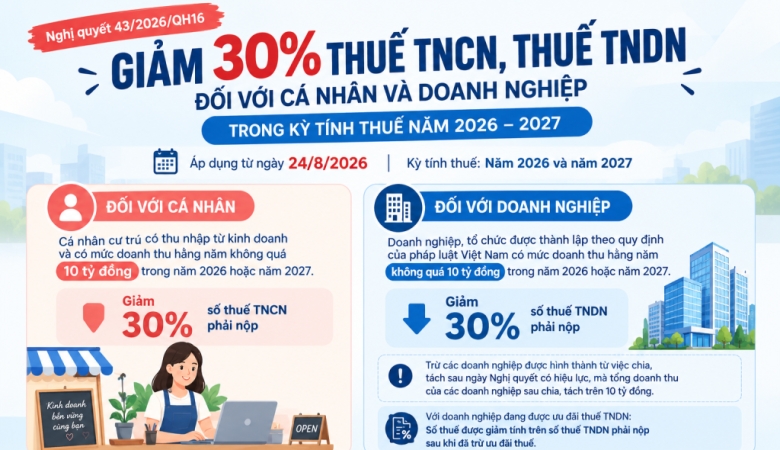
30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT FOR THE 2026-2027

FDI ENTERPRISES ENTITLED TO A 3-YEAR CORPORATE INCOME TAX EXEMPTION FROM THE DATE OF ESTABLISHMENT

FDI ENTERPRISES ENTITLED TO A 3-YEAR CORPORATE INCOME TAX EXEMPTION FROM THE DATE OF ESTABLISHMENT

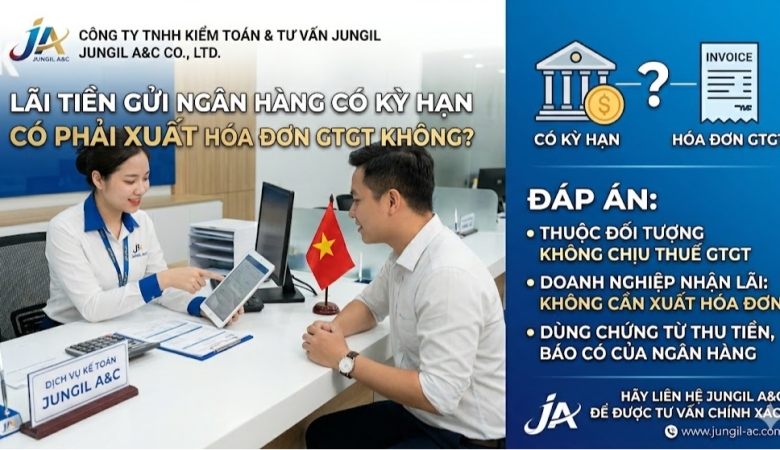
DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

GLOBAL MINIMUN TAX IN VIETNAM

GLOBAL MINIMUN TAX IN VIETNAM

KÊ KHAI THUẾ
KÊ KHAI THUẾ

HƯỚNG DẪN KÊ KHAI, BỔ SUNG ĐIỀU CHỈNH THUẾ GTGT

TIME LIMIT FOR SUPPLEMENTARY TAX DECLARATIONS: REDUCED FROM 10 YEARS TO 5 YEARS

TIME LIMIT FOR SUPPLEMENTARY TAX DECLARATIONS: REDUCED FROM 10 YEARS TO 5 YEARS

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025