PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

Penalty and evidencing for using the illegal invoices of tax risk enterprises

PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

1. The acts of using illegal invoices, according to clause 1, article 4 of Decree 125/2020/ND-CP dated October 19, 2020.

" ...

- Using a goods sale or service provision invoice or document with the creating date stated on such invoice or document from the date on which the tax agency determines that the seller does not operate at the business address registered with the competent state agency;

- Using a goods sale or service provision invoice or document with the creating date stated on such invoice or document is earlier than the date of determining that the invoice- or document-creating party does not operate at the business address registered with the competent state agency, or without tax agency’s notice on the fact that the invoice- or document- creating party does not operate at the business address registered with the competent agency, but the tax agency or the police or other functional agencies have concluded that invoice or document is unlawful."

2. Penalty of the acts of using illegal invoices, according to clause 1, article 28 of Decree 125/2020/ND-CP dated October 19, 2020.

" A fine from VND 20,000,000 to VND 50,000,000 shall bb imposed for the acts of using illegal invoices"

3. Evidencing for invoice of tax risk enterprises, according to office letter No. 11764/CTDON-TTHT dated October 5, 2023 of Dong Nai tax department.

The taxpayer is allowed to declare purchase invoices, if the invoicing date before the date on which it is determined that the invoicing party is not doing business at the address registered with the tax authority. The enterprise has documents proving trading activities between the two parties (such as contract, form and place of delivery goods, means of transport, documents and form of payment ...) and have legal invoices confirmed by competent authorities. 
Related news

PERSONAL INCOME TAX DEDUCTIONS APPLICABLE FROM 2026

PERSONAL INCOME TAX DEDUCTIONS APPLICABLE FROM 2026

DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

DOES INTEREST FROM TERM BANK DEPOSITS REQUIRE THE ISSUANCE OF A VAT INVOICE?

TAX AUDIT DURATION FROM 2026

KEY CHANGES UNDER DESICION NO. 1161/QD-CT

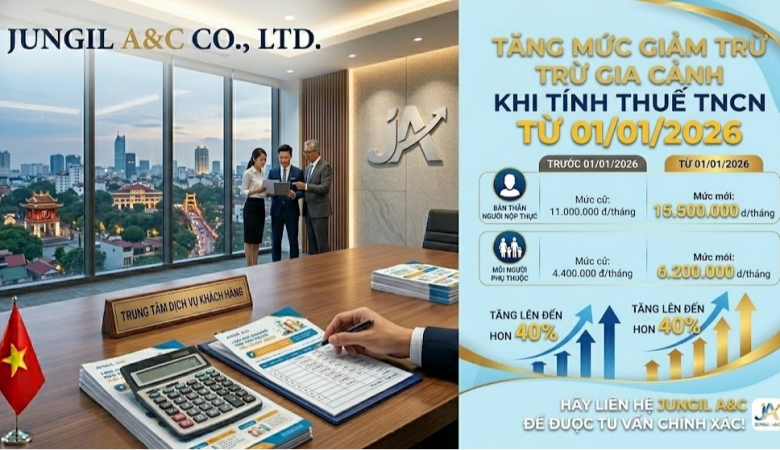
INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026

INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026

DECLARING INVOICE ADJUSTMENTS

DECLARING INVOICE ADJUSTMENTS

BUSINESS HOUSEHOLDS TAX FROM 2026

BUSINESS HOUSEHOLDS TAX FROM 2026

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

DEPENDENT REGISTRATION DOCUMENTS

DEPENDENT REGISTRATION DOCUMENTS

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

SOME NEW POINTS OF THE VAT 2024

SOME NEW POINTS OF THE VAT 2024

VNeID ACCOUNT FOR THE NATIONAL PUBLIC SERVICE PORTAL

VNeID ACCOUNT FOR THE NATIONAL PUBLIC SERVICE PORTAL

VAT REFUND
VAT REFUND

RISK INFORMATION OF VAT REFUND