Vietnamese
 English
 Korean
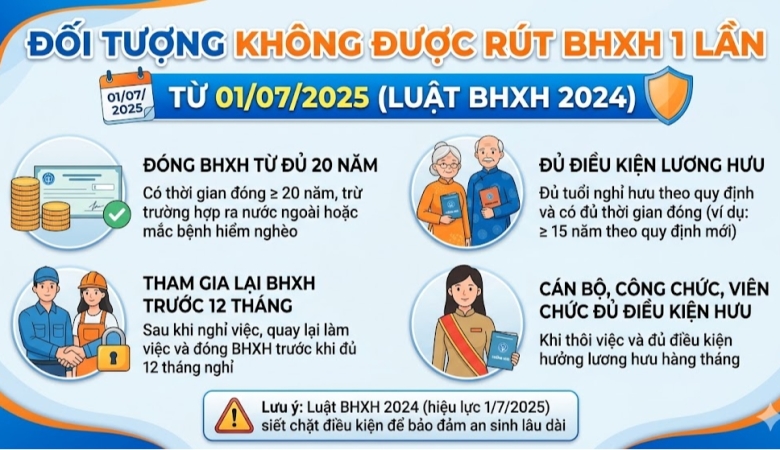
SUBJECTS WILL NOT BE ELIGIBLE FOR LUMP-SUM SOCIAL INSURANCE ALLOWANCE
Pursuant to Clause 1, Article 70 of the Law on Social Insurance 2024 (effective from July 1, 2025), employees who have stopped participating in social insurance and have a request for lump-sum social insurance allowance if they satisfy one of the following conditions:
- Employees reach the retirement age but have paid social insurance for less than 15 years;
- Employees emigrate from Vietnam to a foreign country;
- Employees have one of the following diseases: cancer, polio, decompensated cirrhosis, severe tuberculosis, AIDS;
- Employees have ≥ 81% work capacity reduction; or severe disability;
- Employees who have paid social insurance before July 1, 2025 for less than 20 years and do not participate in voluntary social insurance after 12 months.
- The cases specified in points d, đ and e, Clause 1, Article 2 of the Law on Social Insurance 2024 (officers, non-commissioned officers, regular militia, etc.), is not covered by compulsory social insurance upon demobilization or resignation, does not participate in voluntary social insurance, and is not eligible for pension.
>> Thus, from July 1, 2025, the following subjects will not be eligible for lump-sum social insurance allowance:
- Employees who have paid social insurance for 20 years or more, except in cases of emigrating from Vietnam to a foreign country or suffering from one of the life-threatening diseases.
- Employees who have participated in social insurance before July 1, 2025 and have paid social insurance for less than 20 years but the period of leave from work is less than 12 months. Except for those who reach the retirement age but have not paid social insurance for 15 years, emigrate from Vietnam to a foreign country or have one of the life-threatening diseases.
- Employees who start participating in social insurance from July 1, 2025, after 1 year of unemployment, no longer participate in social insurance but have not paid social insurance for 20 years. Except for those who reach the retirement age but have not paid social insurance for 15 years, emigrate from Vietnam to a foreign country or have one of the life-threatening diseases.
- Officers, non-commissioned officers, regular militiamen, etc., when demobilized or resignation, are eligible for pension, except in cases of emigrating from Vietnam to a foreign country or suffering from one of the life-threatening diseases.