OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026
 

From 01 January 2026: Overtime pay is exempt from PIT – however, “unlawful overtime” may be excluded from the exemption.

From the 2026 tax period (applicable from 01 January 2026 to resident individuals), wages paid for night work, overtime work, and wages/salaries paid for days of unused statutory leave are classified as income exempt from Personal Income Tax (“PIT”) pursuant to Clause 8, Article 4 of the 2025 Law on Personal Income Tax (Law No. 109/2025/QH15).

However, enterprises should pay special attention to the following: for “overtime pay” to be regarded as lawful overtime income and thus eligible for PIT exemption, the organization of overtime work must comply with the statutory limits on overtime under current labor laws.

Limits on Overtime under Article 107 of the 2019 Labor Code and Article 4 of Decree No. 45/2013/ND-CP

Daily working time basis: Overtime hours must not exceed 50% of the normal working hours in one day.

Weekly working time basis: The total normal working hours and overtime must not exceed 12 hours per day and 40 hours per month.

Overtime on weekly days off, public holidays, and Tet holidays: Must not exceed 12 hours per day.

Total overtime hours of an employee: Must not exceed 200 hours per year.

Special cases: For enterprises operating in certain sectors such as manufacturing and processing of textiles, garments, leather and footwear, electrical and electronic products; processing of agricultural, forestry, salt, and aquatic products, etc., overtime may be organized up to 300 hours per year. In such cases, the enterprise is required to notify in writing the Department of Labor, Invalids and Social Affairs where the enterprise is headquartered, no later than 15 days from the date of implementation.
Related news

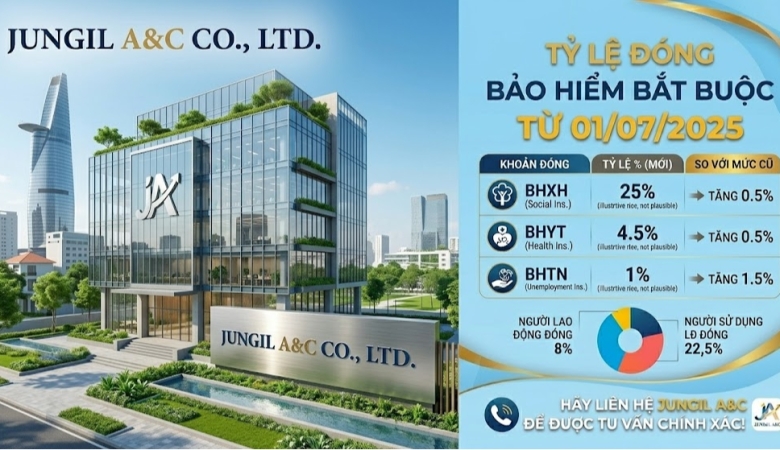
COMPULSORY INSURANCE PREMIUM

COMPULSORY INSURANCE PREMIUM

CANCELLATION OF VAT REFUND APPLICATIONS

CANCELLATION OF VAT REFUND APPLICATIONS AND CARRY-FORWARD OF VAT CREDITS

THE SPOT IMPORT AND EXPORT GOODS CONDUCTED BEFORE 1 JULY 2025

THE SPOT IMPORT AND EXPORT GOODS

TAX EXAMINATION, INSPECTION AT OFFICES OF TAXPAYERS

Tax examination, inspection at offices of taxpayers

GLOBAL MINIMUN TAX IN VIETNAM

GLOBAL MINIMUN TAX IN VIETNAM

VAT PAYMENT DEFERRAL FOR 2026

VAT PAYMENT DEFERRAL FOR 2026

PERSONAL INCOME TAX
PERSONAL INCOME TAX

NON-TAXABLE EMPLOYMENT INCOME IN 2026

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

GENERAL DEPARTMENT OF TAXATION GUIDES FOR TAX EXEMPTIONS, EXTENSIONS AND REDUCTIONS AFFECTED BY TYPHOON YAGI

GENERAL DEPARTMENT OF TAXATION GUIDES FOR TAX EXEMPTIONS, EXTENSIONS AND REDUCTIONS AFFECTED BY TYPHOON YAGI

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS FROM JULY 1, 2026

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS

TIME FOR ISSUING INVOICES AND DECLARING REVENUE OF EXPORT GOODS

The time of issuing e-invoices and declaring revenue of export goods according to official letter No. 4890/TCT-KK

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025