Vietnamese
 English
 Korean
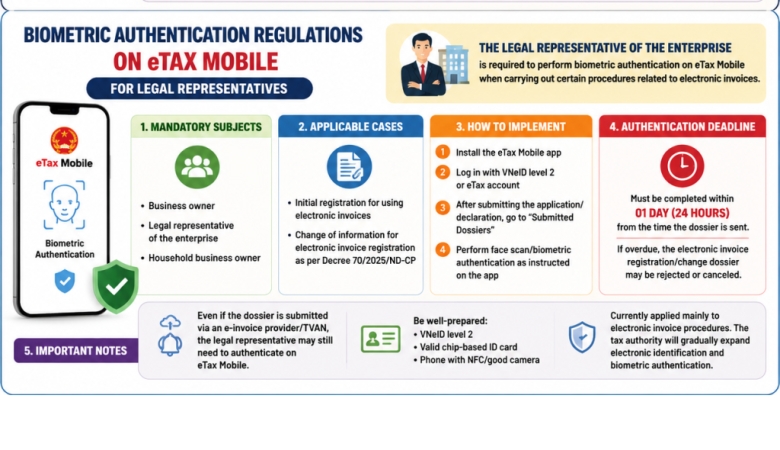
BIOMETRIC AUTHENTICATION REGULATIONS ON eTAX MOBILE
Currently, the tax authority is implementing biometric authentication requirements on the eTax Mobile application for certain electronic invoice procedures, particularly those involving the legal representative of an enterprise.
The main points are as follows:
Subjects required to complete biometric authentication:
- Business owners
- Legal representatives of enterprises
- Household business owners
Applicable cases:
- Initial registration for the use of electronic invoices
- Changes to electronic invoice registration information in accordance with Decree No. 70/2025/ND-CP
Implementation procedure:
- Install the eTax Mobile application
- Log in using a Level 2 VNeID account or an electronic tax account
- After submitting the application/declaration, access the “Submitted Dossiers” section
- Perform facial scanning/biometric authentication following the instructions on the application
Authentication deadline:
- In general, authentication must be completed within 01 day or 24 hours from the time the dossier is submitted
- If the deadline is exceeded, the electronic invoice registration/change application may be rejected or cancelled
Practical notes:
- Even if the enterprise submits the dossier through an e-invoice service provider or TVAN service provider, the legal representative may still be required to access eTax Mobile to complete biometric authentication
- The legal representative should:
- Have a Level 2 VNeID account
- Possess a valid chip-based Citizen ID Card
- Use a mobile phone with NFC/camera functionality to facilitate authentication
At present, this requirement mainly applies to electronic invoice procedures and not to all tax transactions on eTax. However, the tax authority is expected to gradually expand electronic identification and biometric authentication requirements for corporate taxpayers in the future.