Vietnamese
 English
 Korean
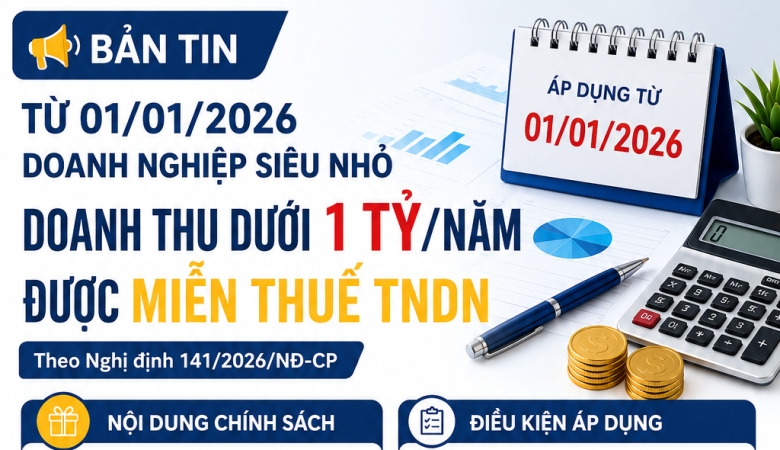
ENTERPRISES WITH ANNUAL REVENUE OF VND 1 BILLION OR LESS ARE EXEMPT FROM CORPORATE INCOME TAX FROM 2026
Under Decree 141/2026/ND-CP amending Decree 320/2025/ND-CP
1. New CIT Exemption for Small Businesses
On 29 April 2026, the Government issued Decree 141/2026/ND-CP amending and supplementing Decree 320/2025/ND-CP guiding the implementation of the Law on Corporate Income Tax.
Under the new regulation, income earned by enterprises and organizations established under Vietnamese law with total annual revenue of VND 1 billion or less will be exempt from Corporate Income Tax (CIT).
This policy is considered a significant support measure for micro-enterprises, startups, and household businesses converting into enterprises.
2. Determination of Annual Revenue Threshold
The annual revenue threshold for CIT exemption includes:
- Revenue from sale of goods;
- Revenue from service provision;
- Financial income;
- Other income.
Please note:
- Revenue deductions are excluded;
- The basis is the Business Performance Appendix attached to the CIT finalization return of the immediately preceding fiscal year.
3. Enterprises Operating for Less Than 12 Months
For enterprises operating less than 12 months in the preceding tax year:
The annual revenue shall be annualized using the following formula:
(Actual revenue / Actual operating months) × 12 months
In addition:
- Newly established enterprises;
- Enterprises undergoing conversion of legal form;
- Change of ownership;
- Merger, consolidation, division, or separation;
will still have the relevant month counted as a full operating month.
4. Newly Established Enterprises Are Exempt from Provisional CIT Payment
Under Decree 141/2026/ND-CP:
If a newly established enterprise expects its annual revenue not to exceed VND 1 billion, it is not required to make provisional CIT payments during the year.
At the end of the tax period:
- If actual revenue exceeds VND 1 billion;
- The enterprise must declare and finalize CIT in accordance with regulations.
However:
- No late payment interest will be imposed on the additionally payable tax amount.
This regulation helps reduce cash flow pressure and administrative burden for newly established businesses.
5. Cases Not Eligible for CIT Exemption
The CIT exemption does not apply to:
- Subsidiaries; or
- Enterprises having related-party relationships;
where the related enterprises do not satisfy the revenue condition for tax exemption.
This regulation is intended to prevent abuse of tax incentives through artificial business restructuring or enterprise splitting.
Businesses should review their revenue structure, operating model, and related-party relationships to assess eligibility for the tax exemption.