ACCOUNTING FOR MICRO ENTERPRISES

ACCOUNTING FOR MICRO ENTERPRISES

ACCOUNTING FOR MICRO ENTERPRISES

CIRCULAR 58/2026/TT-BTC – NEW ACCOUNTING REGULATIONS FOR MICRO ENTERPRISES

On July 1, 2026, Circular 58/2026/TT-BTC officially takes effect, providing accounting regulations applicable to micro enterprises in Vietnam. The Circular applies to fiscal years beginning on or after July 1, 2026.

1. Accounting Books Requirements

Depending on the VAT and Corporate Income Tax (“CIT”) declaration methods, micro enterprises shall apply different accounting books.

Case 1: Enterprises paying VAT and CIT based on percentage of revenue

  • Sales revenue book.

Case 2: Enterprises paying VAT based on revenue percentage and CIT based on taxable income

  • Sales revenue book;
  • Revenue and expense ledger;
  • Inventory ledger;
  • Cash ledger.

Case 3: Enterprises applying VAT credit method and CIT based on revenue percentage

  • Revenue and expense ledger;
  • VAT liability tracking book.

Case 4: Enterprises applying VAT credit method and CIT based on taxable income

  • Revenue and expense ledger;
  • Inventory ledger;
  • Cash ledger;
  • VAT tracking book.

2. Accounting Documents

In addition to invoices and purchase lists for goods/services without invoices, enterprises may also use:

  • Receipt vouchers;
  • Payment vouchers;
  • Goods receipt notes;
  • Goods delivery notes.

3. Financial Statements

Micro enterprises paying CIT based on taxable income must prepare and submit annual financial statements within 90 days from the fiscal year-end.

For enterprises paying CIT based on revenue percentage, annual financial statements are not mandatory for submission to authorities.

4. Effective Date

The Circular takes effect from July 1, 2026 and applies to fiscal years beginning on or after this date.
Related news

OFFSETTING LOSSES AND LOSS CARRYFORWARD UNDER DECREE 320/2025/ND-CP

OFFSETTING LOSSES AND LOSS CARRYFORWARD UNDER DECREE 320/2025/ND-CP

Q2/2026 PIT DECLARATION

Q2/2026 PIT DECLARATION

DEPENDENT REGISTRATION DOCUMENTS

DEPENDENT REGISTRATION DOCUMENTS

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

CORPORATE INCOME TAX (CIT) RATES UNDER DECREE 320/2025/ND-CP

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

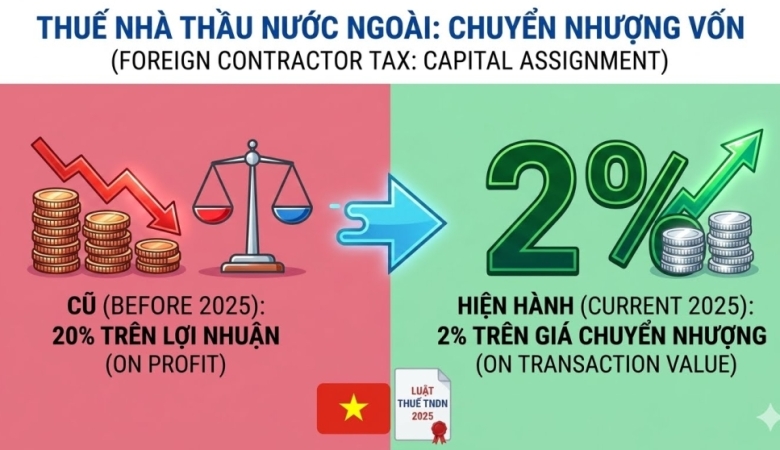
CAPITAL TRANSFER TAXATION

CAPITAL TRANSFER TAXATION

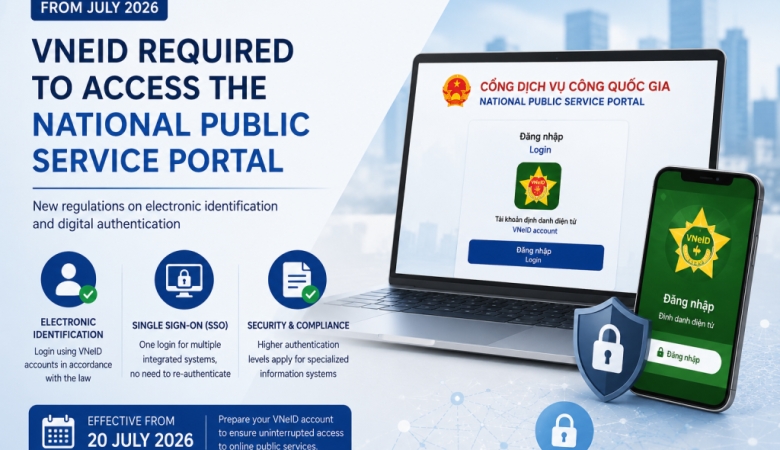
VNeID ACCOUNT FOR THE NATIONAL PUBLIC SERVICE PORTAL

VNeID ACCOUNT FOR THE NATIONAL PUBLIC SERVICE PORTAL

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

REGIONAL MINIMUM WAGE INCREASE BY 6% FROM 01/07/2024

REGIONAL MINIMUM WAGE INCREASE BY 6% FROM 01/07/2024

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

SUPPLEMENTING TAX DECLARATIONS AFTER ISSUANCE OF AN INSPECTION CONCLUSION OR DECISION

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025

THE PROCEDURE FOR AN EXTENSION OF TAX PAYMENT IN 2025