Vietnamese
 English
 Korean
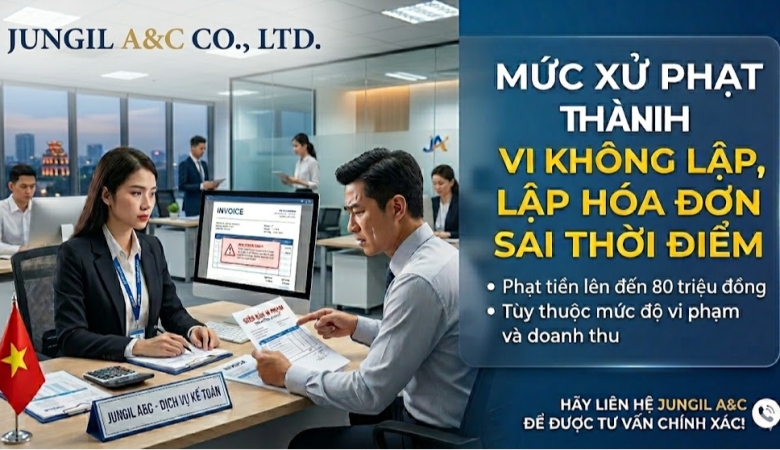
PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME EFFECTIVE FROM JANUARY 16, 2026
On December 02, 2025, the Government issued Decree No. 310/2025/ND-CP amending and supplementing several articles of Decree No. 125/2020/ND-CP dated October 19, 2020 on administrative penalties for violations related to taxation and invoices, including new provisions on penalties for the act of failing to issue invoices or issuing invoices at the incorrect time.
Accordingly, the act of failing to issue invoices or issuing invoices at the incorrect time is no longer sanctioned per invoice. The new regulations specify the level of penalties based on particular groups of invoice quantities, with a maximum penalty not exceeding VND 80,000,000.
Administrative penalties for invoice issuance violations are categorized into two groups: invoices for sales of goods and provision of services with payment, and invoices for goods given, donated, gifted, used for promotion, advertising, or other non-payment transactions. This classification ensures clarity in the nature of the transaction, volume of violations, and the appropriate application of penalties, thereby promoting transparency and consistency in handling invoice-related violations.
The penalties for failure to issue invoices or issuing invoice at the incorrect time applicable from January 16, 2026 are as follows:
- Group: Issuing invoices when selling goods or providing services.
| Number of invoices | Penalties for failure to issue invoices | Penalties for issuing invoices at the incorrect time. |
| 01 invoice | A fine ranging from VND 1,000,000 to VND 2,000,000. | A fine ranging from VND 500,000 to VND 1,500,000. |
| From 02 to fewer than 10 invoices | A fine ranging from VND 2,000,000 to VND 10,000,000. | A fine ranging from VND 2,000,000 to VND 5,000,000. |
| From 10 to fewer than 20 invoices | A fine ranging from VND 10,000,000 to VND 30,000,000. | A fine ranging from VND 5,000,000 to VND 15,000,000. |
| From 20 to fewer than 50 invoices | A fine ranging from VND 30,000,000 to VND 50,000,000. | A fine ranging from VND 15,000,000 to VND 30,000,000. |
| From 50 invoices or more | A fine ranging from VND 60,000,000 to VND 80,000,000. | |
| From 50 to fewer than 100 invoices | A fine ranging from VND 30,000,000 to VND 50,000,000. | |
| From 100 invoices or more | A fine ranging from VND 50,000,000 to VND 70,000,000. |
- Group: Issuing invoices for goods and services used for promotion, advertising, samples; goods and services used for giving, gifting, donation, exchange, salary payment in kind for employees, and internal consumption (excluding internal circulation of goods for continued production process); delivery of goods as loan, borrowing, or returned goods.
| Number of invoices | Penalties for failure to issue invoices | Penalties for issuing invoices at the incorrect time. |
| 01 invoice | Warning imposed | Warning imposed |
| From 02 to fewer than 10 invoices | A fine ranging from VND 1,000,000 to VND 2,000,000. | A fine ranging from VND 500,000 to VND 1,500,000. |
| From 10 to fewer than 50 invoices | A fine ranging from VND 2,000,000 to VND 10,000,000. | A fine ranging from VND 2,000,000 to VND 5,000,000. |
| From 50 to fewer than 100 invoices | A fine ranging from VND 10,000,000 to VND 30,000,000. | A fine ranging from VND 5,000,000 to VND 15,000,000. |
| From 100 invoices or more | A fine ranging from VND 30,000,000 to VND 50,000,000. | A fine ranging from VND 15,000,000 to VND 30,000,000. |