PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

Penalty and evidencing for using the illegal invoices of tax risk enterprises

PENALTY AND EVIDENCING FOR USING THE ILLEGAL INVOICES OF TAX RISK ENTERPRISES

1. The acts of using illegal invoices, according to clause 1, article 4 of Decree 125/2020/ND-CP dated October 19, 2020.

" ...

- Using a goods sale or service provision invoice or document with the creating date stated on such invoice or document from the date on which the tax agency determines that the seller does not operate at the business address registered with the competent state agency;

- Using a goods sale or service provision invoice or document with the creating date stated on such invoice or document is earlier than the date of determining that the invoice- or document-creating party does not operate at the business address registered with the competent state agency, or without tax agency’s notice on the fact that the invoice- or document- creating party does not operate at the business address registered with the competent agency, but the tax agency or the police or other functional agencies have concluded that invoice or document is unlawful."

2. Penalty of the acts of using illegal invoices, according to clause 1, article 28 of Decree 125/2020/ND-CP dated October 19, 2020.

" A fine from VND 20,000,000 to VND 50,000,000 shall bb imposed for the acts of using illegal invoices"

3. Evidencing for invoice of tax risk enterprises, according to office letter No. 11764/CTDON-TTHT dated October 5, 2023 of Dong Nai tax department.

The taxpayer is allowed to declare purchase invoices, if the invoicing date before the date on which it is determined that the invoicing party is not doing business at the address registered with the tax authority. The enterprise has documents proving trading activities between the two parties (such as contract, form and place of delivery goods, means of transport, documents and form of payment ...) and have legal invoices confirmed by competent authorities. 
Related news

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

SOME NEW POINTS ON VAT (VALUE-ADDED TAX) FROM JULY 1, 2025

SUBJECTS WILL NOT BE ELIGIBLE FOR LUMP-SUM SOCIAL INSURANCE ALLOWANCE

SUBJECTS WILL NOT BE ELIGIBLE FOR LUMP-SUM SOCIAL INSURANCE ALLOWANCE

THE LIST OF PRIORITIZED SUPPORTING PRODUCTS DOMESTICALLY MANUFACTURED BEFORE JANUARY 01, 2015

The list of prioritized supporting products domestically manufactured before January 1, 2015

LIST OF AREAS ELIGIBLE FOR INVESTMENT INCENTIVES

List of areas eligible for investment incentives

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS FROM JULY 1, 2026

INVOICES FOR GOODS GIVEN, DONATED, PRESENTED AND PROMOTIONAL GOODS

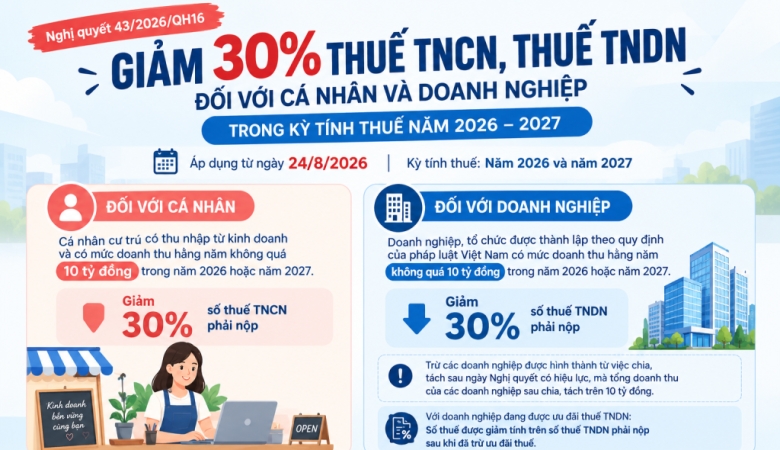
30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT FOR THE 2026-2027

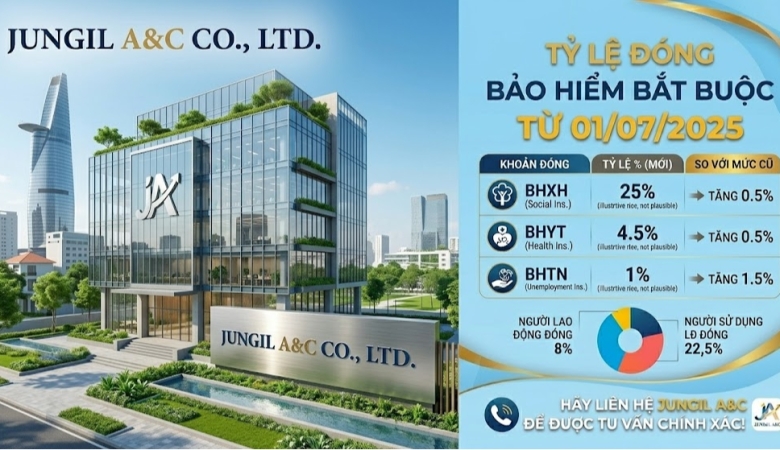
COMPULSORY INSURANCE PREMIUM

COMPULSORY INSURANCE PREMIUM

PROCEDURE FOR HANDLING ERRORS INVOICES ACCORDING TO DECREE 70/2025/ND-CP

PROCEDURE FOR HANDLING ERRORS INVOICES ACCORDING TO DECREE 70/2025/ND-CP

TIME FOR ISSUING INVOICES AND DECLARING REVENUE OF EXPORT GOODS

The time of issuing e-invoices and declaring revenue of export goods according to official letter No. 4890/TCT-KK

EMPLOYEES' WELFARE
EMPLOYEES' WELFARE

EMPLOYEES' WELFARE

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

OVERTIME WAGES EXEMPT FROM PERSONAL INCOME TAX FROM 2026

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT

SUPPLEMENTING VAT DECLARATION RELATED TO THE AMOUNT OF REFUNDABLE VAT