30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT FOR THE 2026-2027

30% REDUCTION IN PIT FOR BUSINESS INDIVIDUALS AND CIT FOR THE 2026-2027

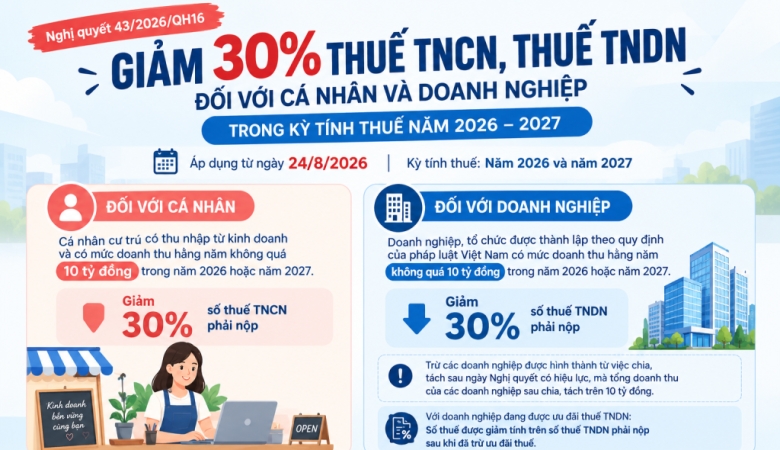
Under Resolution No. 43/2026/QH16, effective from 24 August 2026, eligible business individuals and enterprises are entitled to a 30% reduction in personal income tax (PIT) or corporate income tax (CIT) payable for the 2026 and 2027 tax years.

This tax relief applies to individuals and enterprises with annual revenue of no more than VND 10 billion.

1. 30% PIT Reduction for Business Individuals

Resident individuals earning income from business activities are entitled to a 30% reduction in PIT payable if they meet the following conditions:

  • They are resident individuals earning income from business activities; and
  • Their annual revenue does not exceed VND 10 billion in 2026 or 2027.

The reduction applies to the 2026 and 2027 tax years.

2. 30% CIT Reduction for Enterprises

Enterprises and organizations established under Vietnamese law are entitled to a 30% reduction in CIT payable if their annual revenue does not exceed VND 10 billion in 2026 or 2027.

Enterprises formed through division or separation

The tax reduction does not apply to enterprises established through the division or separation of an enterprise after the effective date of the Resolution if the combined annual revenue of the enterprises after the division or separation exceeds VND 10 billion.

Therefore, enterprises should carefully assess their revenue and corporate restructuring activities when determining eligibility for the tax reduction.

3. Enterprises Already Enjoying CIT Incentives

For enterprises currently benefiting from CIT incentives under the Law on Corporate Income Tax or other laws and resolutions of the National Assembly, the 30% reduction is calculated based on the CIT payable after deducting applicable tax incentives.

For example, if an enterprise has CIT payable of VND 300 million after applying tax incentives, the tax reduction will be:

VND 300 million × 30% = VND 90 million

The remaining CIT payable will therefore be VND 210 million.
Related news

INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026

INCREASE IN FAMILY DEDUCTIONS FROM JANUARY 01, 2026

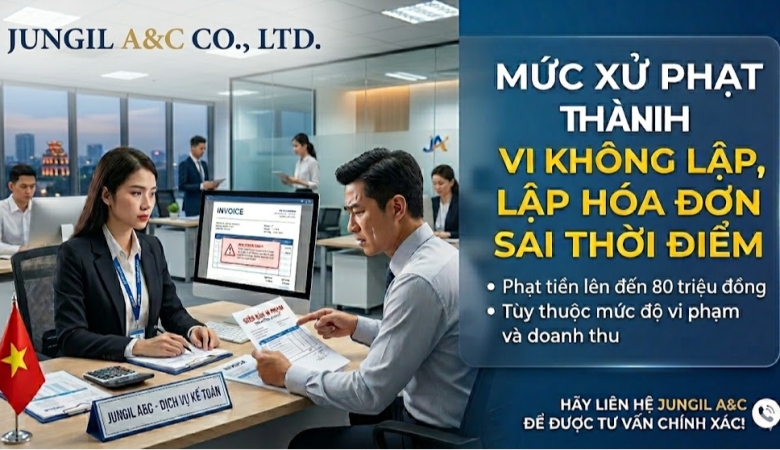
PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME

PENALTIES FOR FAILURE TO ISSUE INVOICES OR ISSUING INVOICES AT THE INCORRECT TIME EFFECTIVE FROM JANUARY 16, 2026

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

CORPORATE INCOME TAX (CIT) EXEMPTION FOR SMALL AND MEDIUM-SIZED ENTERPRISES

CANCELLATION OF VAT REFUND APPLICATIONS

CANCELLATION OF VAT REFUND APPLICATIONS AND CARRY-FORWARD OF VAT CREDITS

TAX EXAMINATION, INSPECTION AT OFFICES OF TAXPAYERS

Tax examination, inspection at offices of taxpayers

TIME FOR ISSUING INVOICES AND DECLARING REVENUE OF EXPORT GOODS

The time of issuing e-invoices and declaring revenue of export goods according to official letter No. 4890/TCT-KK

THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

THE EXPANSION OF THE SUBJECT TO AUDIT THE FINANCIAL STATEMENT

EMPLOYEES' WELFARE
EMPLOYEES' WELFARE

EMPLOYEES' WELFARE

SOME NEW POINTS DEDUCTIBLE EXPENSES UNDER DECREE 320/2025/ND-CP

SOME NEW POINTS REGARDING DEDUCTIBLE EXPENSES WHEN CALCULATING CORPORATE INCOME TAX UNDER DECREE 320/2025/ND-CP

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

HOW TO CALCULATE THE VAT REFUND FOR EXPORTED GOODS AND SERVICES

DECLARING INVOICE ADJUSTMENTS

DECLARING INVOICE ADJUSTMENTS

VAT REFUND
VAT REFUND

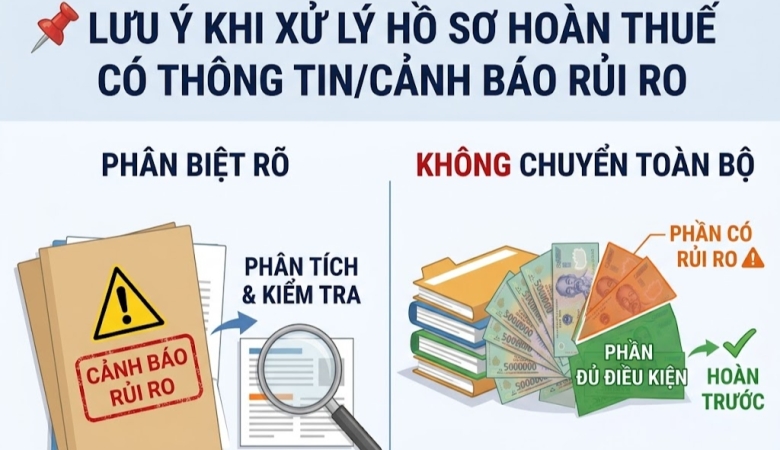
RISK INFORMATION OF VAT REFUND